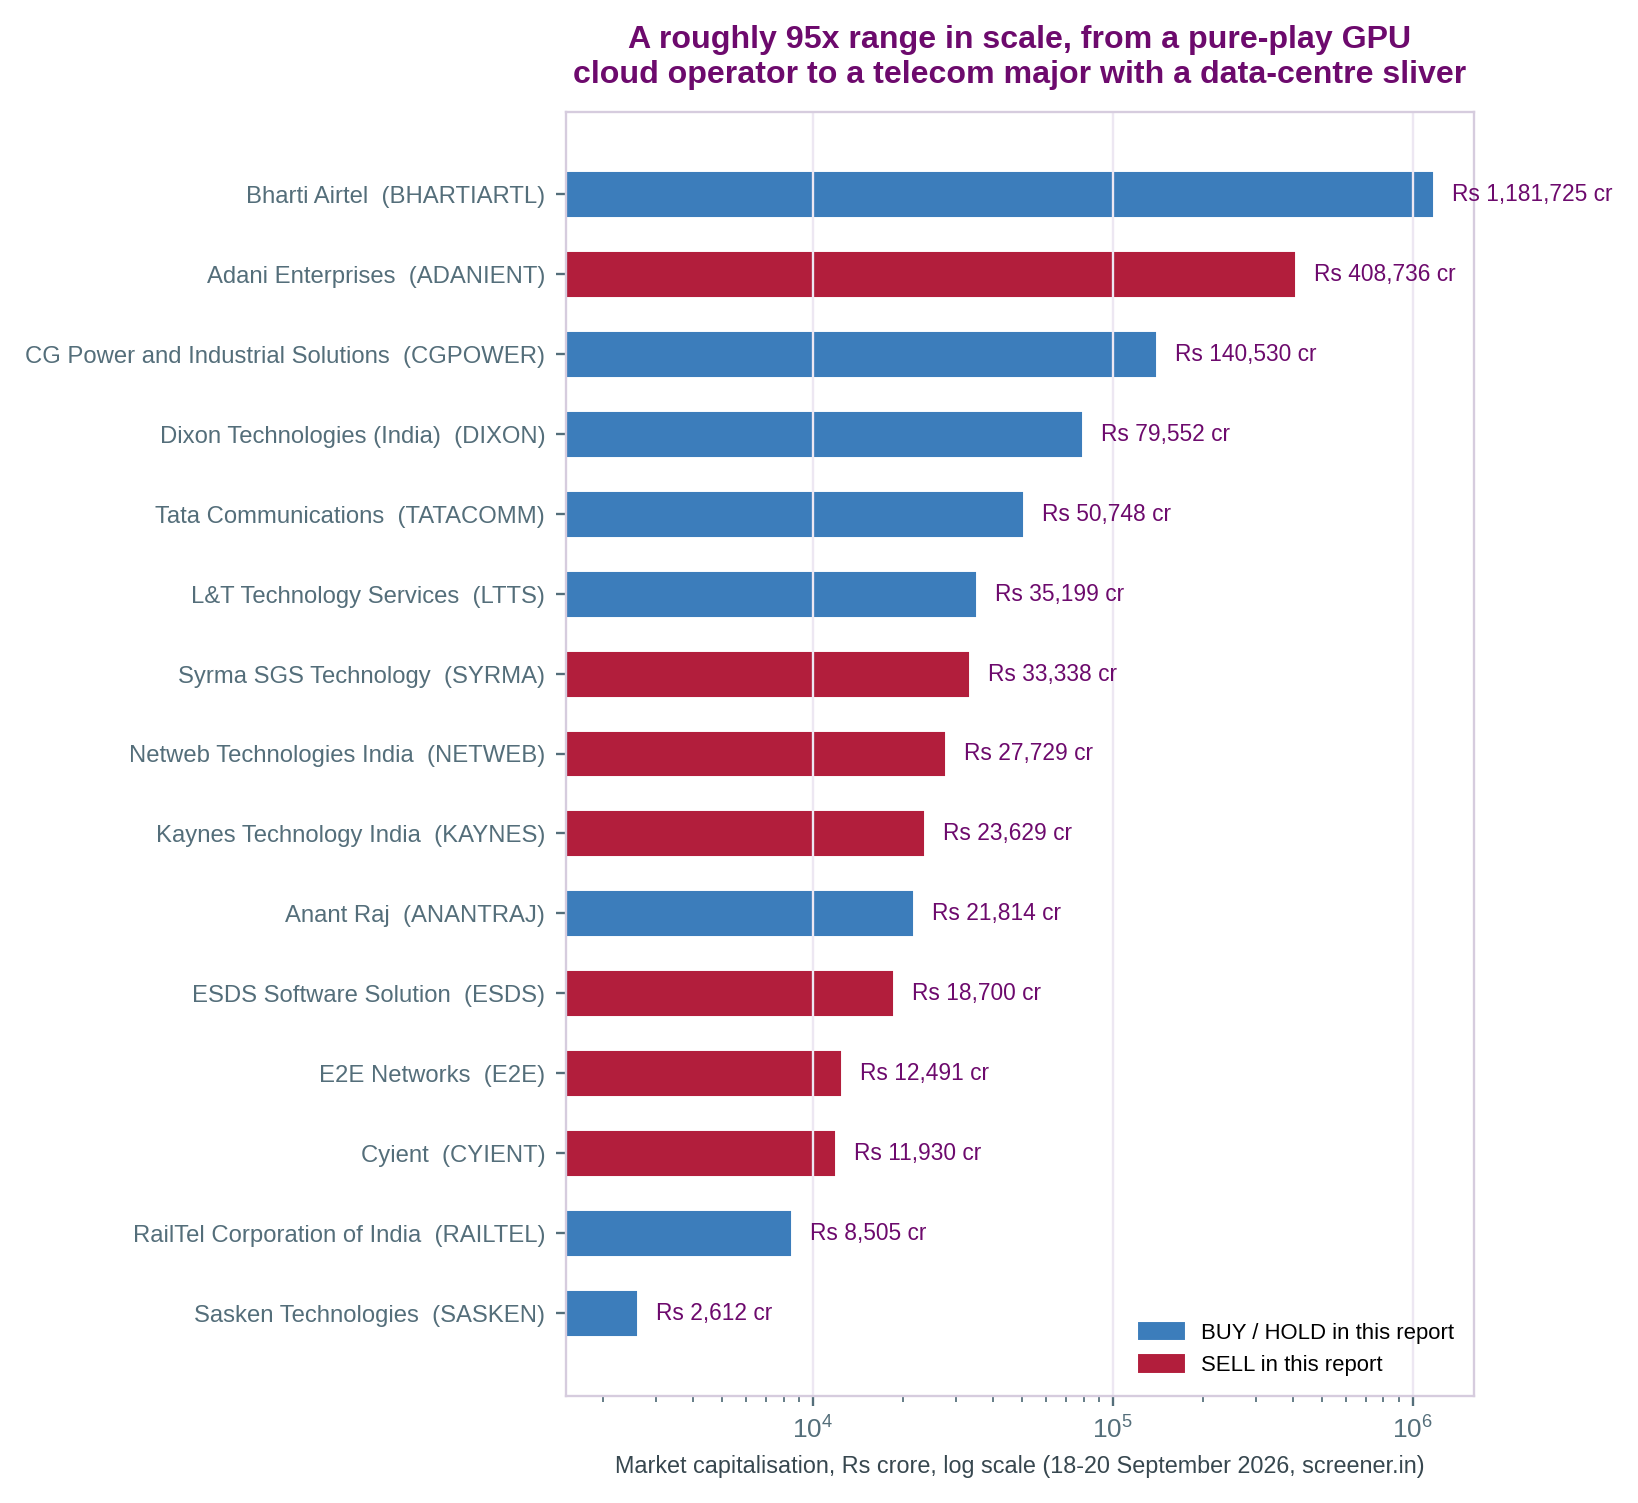
Fifteen NSE/BSE-listed companies touch this value chain today, from a ₹11.8 lakh crore telecom major with a sliver of data-centre exposure to a ₹2,600 crore engineering-services specialist. This report grew from an original eight-company universe — chip/server assembly, packaging and design services — to add seven more spanning GPU cloud, data-centre-adjacent telecom infrastructure, and diversified conglomerates with a real but often small data-centre angle. They range across nearly every rung of the value ladder in §5, and — even more than in the original eight-company version of this report — market capitalisation on its own now tells you almost nothing about how much of a company's business is actually AI-compute-stack exposure, or how exposed its valuation already is to that story.
The original eight-company version of this report split its universe into two buckets. Adding seven companies spanning GPU cloud, data-centre-adjacent telecom and large diversified conglomerates makes a third bucket necessary — companies where the "AI/data-centre" story is real but genuinely too small or too indirect to be the reason to own the stock. Splitting all fifteen this way — based on segment disclosure where a company breaks one out, and on business description and this report's own materiality findings where it does not — produces a cleaner picture than market cap alone:
| AI/data-centre work is close to the identity | A real bet among several | A rounding error, or already divested |
|---|---|---|
| Netweb Technologies — AI/HPC systems are the entire business; FY26 "AI Systems" revenue up 459.6% YoY per company commentary | Dixon Technologies — IT hardware/servers sit inside a ~90%-mobiles-and-EMS revenue base; the Inventec server JV is a genuine but still pre-revenue bet | Bharti Airtel — Nxtra is ~1.1-1.6% of consolidated revenue; a genuine $1bn capital raise and 1GW target sit outside the consolidated financials entirely |
| Kaynes Technology — Kaynes Semicon's OSAT line is a core strategic investment, though its first shipped product is not itself an AI-compute part | CG Power — the CG Semi OSAT joint venture and a ₹900cr US hyperscale transformer order are real but sit inside a much larger transformer/motor/rail business | Tata Communications — the legacy data-centre real-estate business was fully divested; what remains is an unconsolidated 26% STT GDC India stake and a separate, more relevant NVIDIA AI Cloud partnership |
| Syrma SGS Technology — the Giga Computing server-motherboard partnership is a genuine, if early-stage, entry into AI-adjacent hardware | L&T Technology Services — semiconductor and data-centre engineering sit inside the broader "Tech" segment without a separately disclosed AI-specific figure | Adani Enterprises — AdaniConneX's financials are not disclosed or broken out anywhere within AEL's consolidated base; a $15bn Google deal is real but under active, unresolved litigation |
| E2E Networks — India's only pure-play listed GPU cloud; a confirmed NVIDIA/L&T-Vyoma B200 deal and a ~₹1,000cr sovereign-AI contract, though FY26 was a depreciation-driven net loss | Cyient — semiconductor design services and the pending TAO Digital AI acquisition sit inside a larger, currently-shrinking DET/DLM engineering business | |
| ESDS Software Solution — a ~2-week-old listing whose entire growth story rests on one ~25x-revenue contract with an unverified counterparty | Sasken Technologies — a genuine new AI-silicon design win sits inside a company whose FY26 growth was mostly the Borqs acquisition, not organic AI demand | |
| RailTel — data-centre revenue is ~4.7% of a railway-telecom PSU's base, real and growing (+59% YoY) but still small | ||
| Anant Raj — a real-estate landlord scaling ~28MW of operational data centres toward a multi-hundred-MW plan, with a genuine demerger catalyst (Ashok Cloud) — closer to this bucket's "identity" edge than any other company in it, held back only by an unresolved ED probe |
Source: Dart Consultants, from company segment disclosures gathered for each company's own report (Part 4). Where a segment split is not independently confirmed, the company is placed by business description and this report's own materiality findings.
A company where AI/data-centre work is 100% of the identity is not automatically the better investment — it is simply the one where the industry's own margin-compression dynamic (§2-3), and now also its valuation-froth dynamic (E2E Networks, ESDS), cannot hide inside a larger, unrelated business. A company in the third bucket is not automatically a bad investment either — Bharti Airtel and Tata Communications both carry real, separately-justified investment cases — but neither is an AI/data-centre bet in any way that matters to its valuation today, and this report says so plainly rather than stretching the thesis to cover fifteen names uniformly. Read every rating in this section against which bucket, above, the company sits in.
| Company | Ticker | Primary value-chain layer | Market cap (18 Sep 2026) |
|---|---|---|---|
| Bharti Airtel | BHARTIARTL | Telecom; Nxtra data-centre arm (~1-1.6% of revenue) | ₹11,81,725 cr |
| Adani Enterprises | ADANIENT | Diversified conglomerate; AdaniConneX 50:50 JV (DC financials undisclosed) | ₹4,08,736 cr |
| CG Power and Industrial Solutions | CGPOWER | Power/industrial equipment; CG Semi OSAT joint venture | ₹1,40,530 cr |
| Tata Communications | TATACOMM | Telecom/enterprise data; unconsolidated STT GDC stake + NVIDIA AI Cloud partnership | ₹50,748 cr |
| Dixon Technologies (India) | DIXON | EMS; IT-hardware/server manufacturing (Inventec JV) | ₹79,552 cr |
| Syrma SGS Technology | SYRMA | EMS/PCBA; entering server-motherboard manufacturing (Giga Computing) | ₹33,338 cr |
| L&T Technology Services | LTTS | Engineering R&D services; semiconductor design practice | ₹35,199 cr |
| Netweb Technologies India | NETWEB | NVIDIA-certified AI/HPC server systems | ₹27,729 cr |
| Kaynes Technology India | KAYNES | EMS; Kaynes Semicon OSAT (semiconductor packaging) | ₹23,629 cr |
| Anant Raj | ANANTRAJ | Real estate; scaling data-centre operator (~28MW live) | ₹21,814 cr |
| ESDS Software Solution | ESDS | Cloud/AI-GPU hosting, freshly listed Sep 2026 | ~₹18,700 cr |
| Cyient | CYIENT | Engineering services (DET) + design-led manufacturing (DLM); semiconductor design | ₹11,930 cr |
| E2E Networks | E2E | Pure-play listed GPU cloud | ₹12,491 cr |
| RailTel Corporation of India | RAILTEL | Railway telecom PSU; growing data-centre sliver (~4.7% of revenue) | ₹8,505 cr |
| Sasken Technologies | SASKEN | Product engineering; semiconductor hardware design services | ₹2,612 cr |
Sorted by market capitalisation. Source: screener.in and each company's own report in this document, as of 18 September 2026 (ESDS figure reflects its ~2-week-old, still-volatile post-listing trading range — see its own report).
Kaynes Technology carries a confirmed, primary-sourced governance flag — a SEBI settlement order (27 March 2026, ₹23.42 lakh) against its promoter and Executive Vice Chairman for insider-trading/database lapses, alongside a December 2025 related-party-disclosure controversy and a FY26 revenue miss with negative operating cash flow. CG Power's current governance is materially better than its own history — the 2019 accounting-fraud episode under prior (Avantha Group) ownership predates the 2020 Murugappa Group takeover entirely, but remains disclosure-relevant context. Cyient's AI-compute-stack exposure is still mostly a plan, not a result — the $218m TAO Digital acquisition had not closed as of this report's research date. ESDS Software Solution is a ~2-week-old listing already under ASM Stage-1 surveillance for extreme post-listing volatility, built almost entirely on one disclosed contract with an unverified counterparty. Anant Raj had its Delhi office searched by the Enforcement Directorate on 24 April 2026 in a money-laundering case that remains unresolved as of this report's research date — a live overhang on an otherwise attractive data-centre growth and demerger story. Adani Enterprises reported a Q1 FY27 consolidated net loss driven by a $275 million US OFAC sanctions settlement, alongside an unresolved public-interest-litigation challenge to its largest named data-centre deal — the most serious governance/legal red flag of any company in this report. None of this makes any of the six stocks automatically uninvestable; all six are exactly the kind of structural detail this report exists to surface rather than gloss over. Full reports for each of the fifteen companies — financials, governance assessment, SWOT, valuation and rating — follow this primer; see each company's own report for the fullest, most current picture.